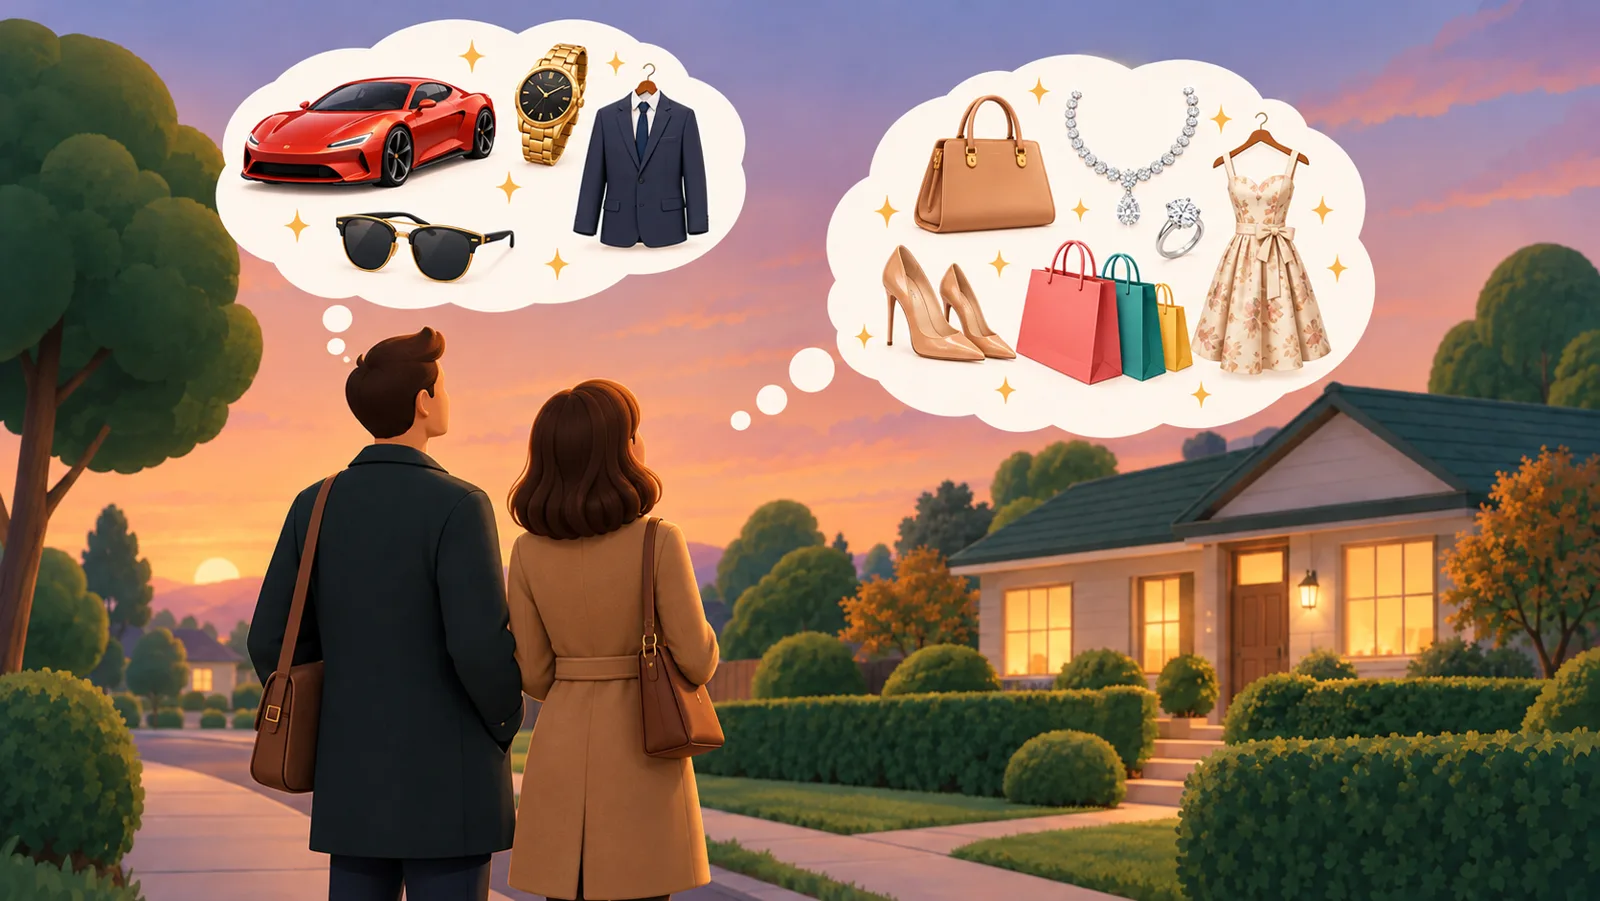
Keeping up with the Joneses is the most expensive habit most households never budget for. It doesn’t show up as a line item. It hides inside the car payment, the kitchen remodel, the kids’ sneakers and the vacation that had to look good online. And no spreadsheet can fix it, because the problem isn’t math. It’s what you value.
That is why living on less starts in your head, not in your wallet. Cut spending without changing your values and the money leaks back out within months. Change your values first, and spending less stops feeling like a sacrifice.
Quick answer
Decide what actually matters to you before you cut anything. Then stop paying for brands and status, stop comparing yourself with your neighbors, and send the money you free up toward savings, independence and a plan B. If you can’t afford it, the Joneses’ approval isn’t worth the debt.
Why your values come before your budget
Most money advice starts with a budget. Track every dollar, set limits, cut the lattes. It works for a few weeks. Then a friend buys a new SUV, a coworker posts photos from Bali, and the budget quietly dies.
The reason is simple. A budget tells you what to spend. Your values decide what you want. When the two disagree, values win every time.
So ask the harder question first: what do you want your money to do for you? For most Future West readers, the honest answers look something like this:
- Fewer money worries and less debt
- Time with family instead of overtime to pay for things
- Security if the economy turns or a job disappears
- The freedom to move, start over or retire early
Notice what is missing from that list: impressing people. Once you see that clearly, a lot of spending loses its pull.
The Joneses were never real
The phrase comes from a newspaper comic strip. Keeping Up with the Joneses by Arthur “Pop” Momand first ran on March 31, 1913. It followed the McGinis family as they tried to match their neighbors, the Joneses. The twist: the Joneses never appeared. They were talked about constantly but never seen.
Momand drew from his own life. He and his wife lived in Cedarhurst, Long Island, “far beyond our means in our endeavor to keep up with the well-to-do class,” as he later put it. They quit the race, moved to a cheap apartment in Manhattan and turned the experience into a strip that ran for about 25 years (Lambiek Comiclopedia).
More than a century later, the joke still holds. The people you compete with are mostly an idea. You don’t see their credit card balances, their arguments about money or how close they are to the edge. You only see the car in the driveway.
What the data says about competing with your neighbors
Economists have tested the Joneses effect directly. A study by Sumit Agarwal, Vyacheslav Mikhed and Barry Scholnick looked at lottery winners in a Canadian province and their closest neighbors, in postal codes with only about 13 households each. The larger the neighbor’s win, the more the people next door borrowed and the more of them went bankrupt in the following years (Federal Reserve Bank of Philadelphia).
An earlier version of the paper found that each extra C$1,000 in prize money raised bankruptcies among close neighbors by 2.4% (Fed in Print). The telling detail is what those neighbors had on their balance sheets when they went broke: more visible assets like houses, cars and motorcycles, but no more cash or pension savings. They spent to be seen, not to be secure.
The study was published in 2020 in The Review of Financial Studies. Its lesson is blunt: when someone near you suddenly has more, the pressure to look equal can push ordinary families into debt they can’t carry.
Skip the brands
Brands are the everyday version of the Joneses. You aren’t only paying for the product. You are paying for the advertising that taught you to want the logo.
The gap is large. According to the Private Label Manufacturers Association, many large consumer-goods companies spend 20 cents or more of every dollar on promotion and advertising, and shoppers save one-third or more by choosing store brands. In blind taste tests by Consumer Reports, store and national brands tied 10 times out of 19, and store brands often cost much less. A 2026 NetCredit comparison of 171 grocery items at Walmart, Target and Kroger found store-brand whole milk about 61% cheaper on average.
Groceries are only the start. The same logic applies to:
- Cars: a reliable used car moves you just as well as a new luxury badge, and someone else has already paid for the steepest depreciation.
- Clothes and shoes: pay for fit and durability, not for a name on the outside.
- Phones and gadgets: last year’s model does almost everything this year’s does.
- Home and kitchen: the store-brand tool, pan or cleaner often comes from the same kind of factory.
There are sensible exceptions. Safety gear, tools you use every day and things that must not fail are worth buying for quality. The test is simple: are you paying for function, or for what the label says about you?
You can’t afford it, and it doesn’t lead anywhere good
A famous line sums it up:
“Too many people spend money they haven’t earned to buy things they don’t want to impress people they don’t like.” — attributed to Will Rogers
The saying is almost a century old. Its first full version appeared in a 1928 newspaper column by the humorist Robert Quillen, and it later became linked to Will Rogers (Quote Investigator). It still describes many households today: long hours at a job you dread, paying for things meant for someone else’s eyes.
Here is the uncomfortable truth about competing with the Joneses: most people who do it can’t afford it. They finance it. The lease, the store card, the “0% for 12 months” offer and the home equity loan all exist because so many people want things before they have paid for them.
And the race has no finish line. There is always a bigger house, a newer car or a family with a better vacation. Each upgrade feels good for a while, then becomes normal. The only things that reliably stay are the payments.
Meanwhile, the real costs pile up out of sight:
- Less freedom: debt ties you to your job, your city and your current life.
- Less security: money spent on display is money missing from your emergency fund.
- More stress: keeping up appearances is tiring, and many of the people you’re impressing are doing the same.
For a household under pressure from inflation, high rents and an uncertain job market, this is the opposite of resilience.
Expect your circle to pull you back
The hardest part of living on less isn’t giving up things. It’s breaking with the values of the people around you. Your spending habits were learned from your family and are reinforced by your friends: where you eat, how you vacation, what car is “normal” and what counts as a good gift. Changing your values means stepping out of that shared picture, and people notice.
Family will have to adjust. You can’t trade in your parents, siblings or in-laws, so be patient and clear. Explain what you’re saving for, keep traditions that matter but make them cheaper, and give them time. Most families come around once they see you’re happier and less stressed, not deprived.
Friends are different. Real friends will adjust too: they’ll swap the expensive restaurant for a dinner at home or a hike, and they’ll respect your goals even if they don’t share them. If a friendship only works when you spend money to keep up, it may not have been a real friendship. Losing it costs less than keeping it.
When you step out of the race, not everyone will cheer. Friends may tease you about the old car. Relatives may ask why you don’t buy nicer things “when you can afford them.” Some of it is habit. Some of it is discomfort: your choice quietly questions theirs.
We wrote about this in Fight or Flight with the image of lobsters in a basket pulling back the one that tries to climb out. Spending works the same way. The pull is real, so decide in advance how you will answer it. “We’re saving for something more important” ends most conversations politely.
Five steps to reset your values
- Write down what matters. Pick your three most important goals for the next five years. Keep the list where you see it when you shop.
- Audit what you buy to be seen. Go through the last three months of statements and mark every purchase that was mainly about how it looks to others. That total is your Joneses tax.
- Run the brand-swap test. For one month, buy the store brand of everything you use regularly. Keep only the name brands you truly miss.
- Use a waiting rule. Wait 48 hours before any non-essential purchase, and 30 days for anything big. Most wants fade. The real needs stay.
- Give the savings a job. Send what you free up to debt repayment, an emergency fund, or a plan B fund for the day you want to move or change course. Money with a purpose is harder to spend on show.
Freedom is the real status symbol
The Joneses can’t take your money unless you hand it over. Once you stop caring what they think, a lot of things get cheaper: your car, your clothes, your house and your stress level.
“Only those who don’t care what others think are truly free.”
A similar line, “Care about what other people think and you will always be their prisoner,” is widely shared as a quote from Lao Tzu. It isn’t in the Tao Te Ching. It comes from Stephen Mitchell’s very loose 1988 English rendering of chapter 9 (Taoistic). The idea stands on its own, though, whoever said it first.
Living on less isn’t about doing without. It’s about choosing what you want your money to buy. For most people, the answer turns out to be freedom.
Frequently asked questions
Is it ever worth paying for a brand?
Yes, when the brand buys real quality you need: safety equipment, tools you use every day, or items where failure is costly. Pay for function and durability, not for the logo.
What if my family or friends judge me for spending less?
Expect it, and don’t argue about it. A short, friendly answer such as “we’re saving for something more important” is usually enough. Family usually adjusts with time. Friends who only stay close while you spend may not be real friends.
Isn’t living on less the same as being cheap?
No. Being cheap means refusing to spend even when it matters. Living on less means spending deliberately on what you value and cutting what you only buy for appearances.
Where should the money I save go first?
Start with high-interest debt and a basic emergency fund. After that, build savings toward the goals on your list, including a plan B fund if moving or changing careers is on your mind.
Note: This article is general information about lifestyle and spending choices, not personal financial advice. For decisions about debt, investments or taxes, talk to a qualified professional.